Essays2026-10-22
The Rise of AI-Native Startups
The shift from selling tools to becoming the industry itself.
- Published
- 2026-10-22
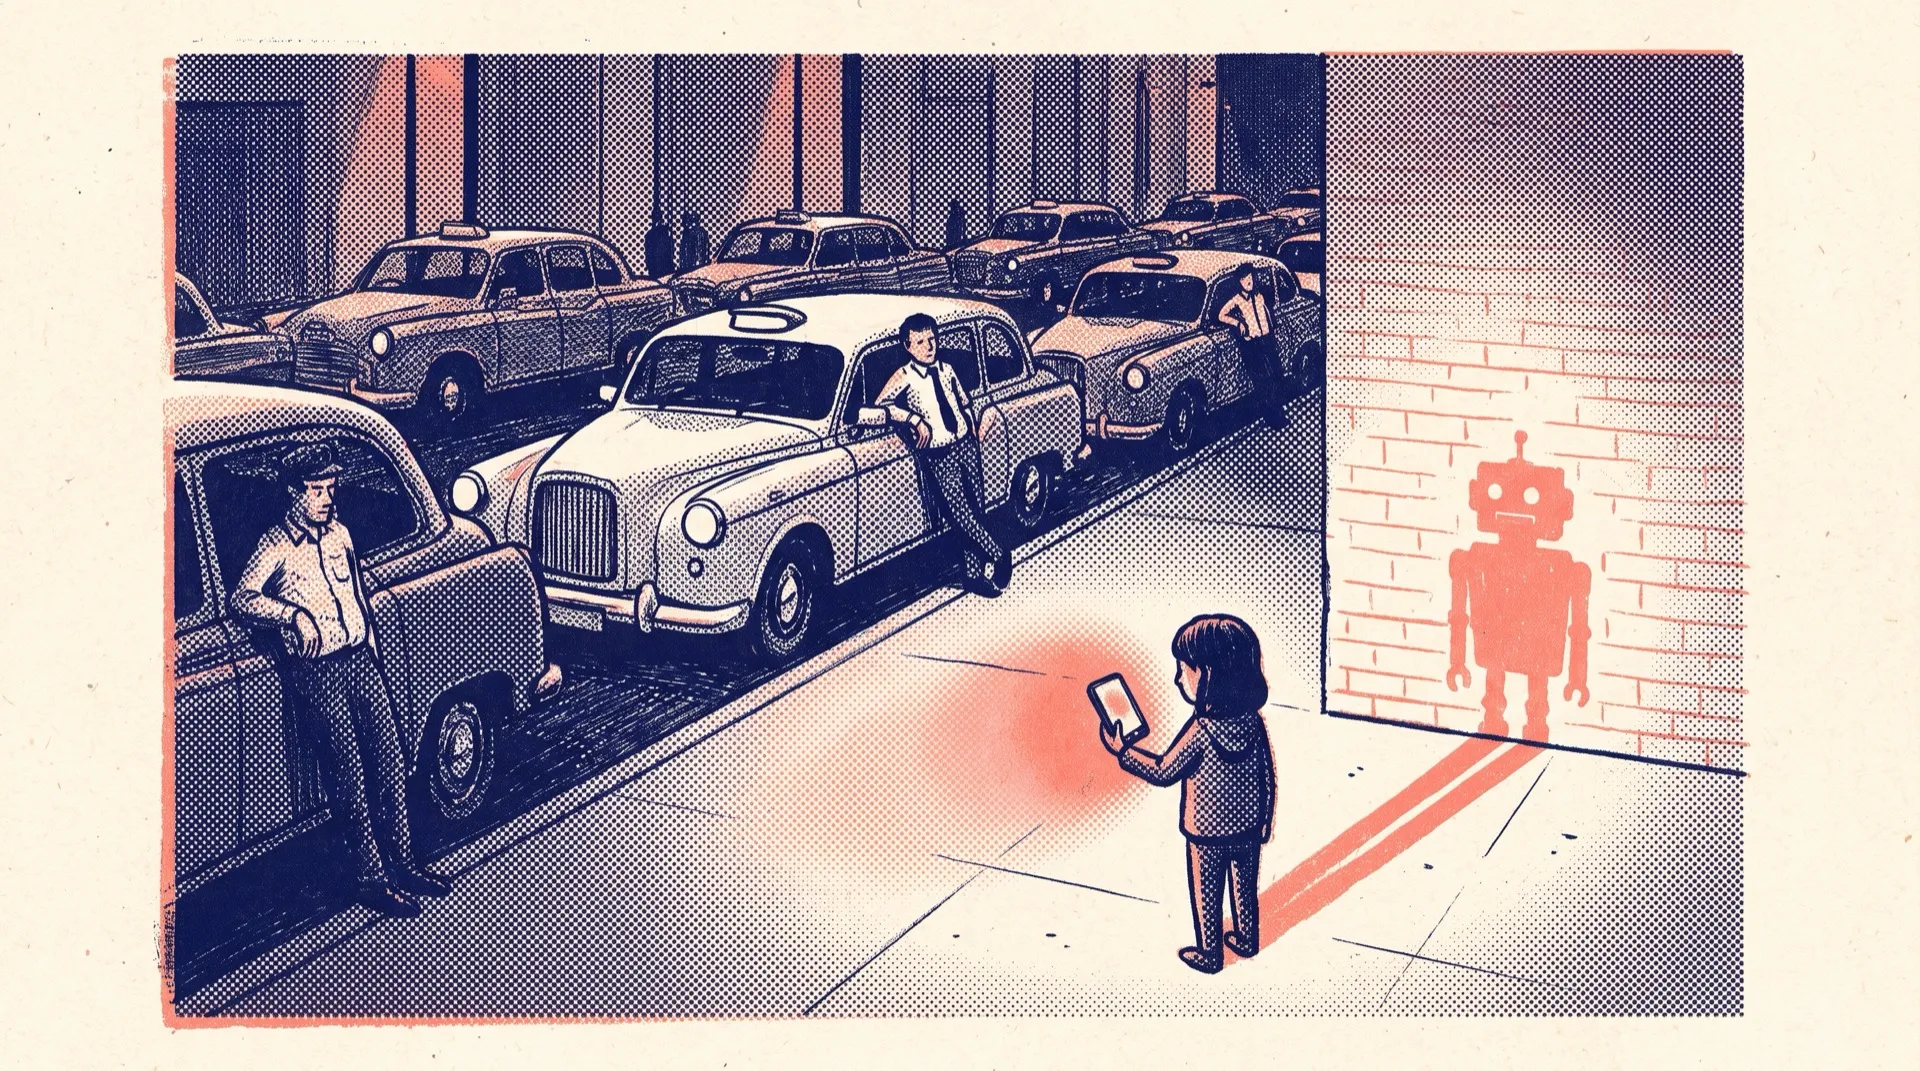
I remember the industry shakeup that took place as the mobile market matured. When smartphones became widespread, a wave of new startups emerged and devoured legacy industries. Among the companies that dominated the market at the time, it was hard to find any that successfully reinvented themselves by adapting to mobile. Their places were taken by new companies born in the mobile environment, which grew into unicorns.
Now, as artificial intelligence matures, the same scene is unfolding. Before incumbents can pull off an internal AI transformation, “AI-native” startups—built from day one around AI agents, software programs that autonomously carry out multi-step tasks assigned by humans—are penetrating the field.
The two scenes look remarkably alike. But there is one critical difference, and that difference makes this reorganization far more painful for incumbents than the mobile shift was. During the mobile era, O2O companies sat on top of existing industries and captured the customer front door. Today’s AI natives, however, do not stop at selling tools; they handle the work itself. Instead of layering over an incumbent industry, they are becoming the industry.
1. What Incumbents Lost in the Mobile Era
O2O companies did not win by outperforming existing industries with superior production technology; they won by capturing the customer’s entry point. The O2O model, connecting online orders to offline service delivery, was epitomized by Uber and Kakao Taxi in rides, Airbnb in lodging, and Baemin in food delivery.
Even when these platforms dominated the market, the people doing the underlying work did not change. Taxi drivers still drove, and restaurants still cooked. The platforms simply sat atop these operations, taking orders and handing them down. Offline operators did all the physical work, yet market leverage and enterprise value shifted almost overnight to the platforms controlling the front door.
On Airbnb’s first day of trading in December 2020, its market valuation at the closing bell exceeded the combined value of the world’s top three publicly traded hotel chains: Marriott, Hilton, and Hyatt. In December 2019, Woowa Brothers, the operator of Baemin, agreed to be acquired by Germany’s Delivery Hero at a valuation of approximately $4 billion. Legacy companies with massive physical assets and thousands of employees were pushed aside by young platforms armed with software alone.
In The Innovator’s Dilemma (1997), Clayton Christensen pointed out that market leaders fall behind not because they fail to understand new technology, but because they focus on protecting the customers and business models that generate their current profits. It is difficult to dismantle your own revenue engine. In my view, incumbents during the mobile revolution surrendered their customer touchpoints for that very reason.
Even then, incumbents retained at least some baseline role. They may have lost the customer relationship and had to pay platform fees, but they kept their position as the suppliers who actually performed the work.
2. This Time, They Do the Work Themselves
Today’s AI natives do not settle for taking brokerage fees on top of existing industries. Companies that used to sell software or tools are turning into businesses that deliver the end work themselves.
Consider Norm Ai, which supplied AI agents to the legal and compliance teams of financial institutions like banks, asset managers, and insurance companies. Rather than stopping at software sales, the company launched its own AI-native law firm, Norm Law, in November 2025. It delivers legal services by letting AI agents handle substantive legal tasks like contract review, while licensed attorneys give final approval.
The insurance brokerage Harper, founded in 2024, followed a similar path. The founders initially considered selling AI tools to existing brokers, then pivoted. They chose to get licensed and become brokers themselves. Instead of handing someone a tool, they decided to do the brokering directly.
The customer support company Crescendo took an even more aggressive step. In October 2024, with just over twenty employees, it acquired PartnerHero, a customer support outsourcing firm with roughly 3,000 staff. General Catalyst, the venture firm behind Crescendo, calls this approach a “venture buyout”—acquiring a traditional service firm to rebuild it around AI.
Venture firm Foundation Capital estimates the market for “service as software”—selling finished work rather than tools—at $4.6 trillion. By their calculation, the market for human-delivered services dwarfs the market for software that people use to do that work.
During the mobile era, incumbents could still fall back on being the supplier receiving orders. In domains targeted by AI natives, however, the startups absorb not just customer touchpoints, but the underlying work legacy firms used to sell. The space left for incumbents will be vastly smaller than it was back then.
3. Why Do the Work Instead of Selling Tools
The reason startups are stepping in to deliver services directly, rather than remaining software vendors, is straightforward. Selling AI tools to companies billed by time and headcount means selling a contradictory product: the less the buyer uses it, the better off they are.
Traditional law firms bill for hours worked by attorneys (billable hours), while business process outsourcing (BPO) call centers contract based on headcount. Under this structure, if AI cuts execution time in half, billable revenue for the law firm or call center collapses by half before the client ever sees productivity gains. For incumbents, software that maximizes efficiency feels like a noose.
AI-native firms, on the other hand, change the pricing model from the ground up. The founder of Norm Ai, which created Norm Law, explains that they set fixed prices up front per unit of work, such as a single transaction or an individual contract review. They price the deliverable, not the hours invested. Crescendo similarly bills per resolved ticket rather than by handle time, with AI handling customer inquiries first and routing only unresolved issues to human agents.
The outsized productivity gains generated by AI accrue not to companies that sell tools, but to those that control the pricing structure. That is why startups take direct control of the service instead of remaining vendors beholden to reluctant buyers.
Where taxi medallions and hotel rooms once stood as physical barriers against innovation in the mobile era, revenue models based on hourly rates and headcount now stand in their place. Christensen’s innovator’s dilemma has reappeared in an even clearer form.
4. The Internal Wall
Seen through the eyes of internal staff, this contradiction in revenue models sparks intense organizational resistance. In a company that has always sold time as its product, management’s call to “adopt AI and work faster” sounds to employees like a threat to “cut my hours and eliminate my job.” That reaction is entirely natural.
The friction experienced by Konecta, a BPO provider operating customer support across 28 countries, illustrates this clearly. For frontline agents, the rollout of AI felt like job cuts and instability. Sales and operations teams who had built the business on headcount also struggled to embrace a model that threatened their revenue structure. The company adopted BCG’s 10-20-70 rule—which posits that 10% of success comes from algorithms, 20% from tech and data, and 70% from people and processes. It established Konecta Academy to retrain everyone from executives to frontline agents, and created a new role called “Hybrid Agent Manager” to oversee task distribution and handover quality between human agents and AI agents. Over 12 months, it deployed more than 80 generative AI features into production, with over 25,000 employees using AI.
Software companies that do not sell time were not immune either. The CEO of Warp, which develops AI coding tools, had to model his own usage guidelines personally for over three months to win over employees. At financial firm Affirm, when only a few dozen engineers had changed how they worked while the other 800 had not, the company paused non-essential meetings and releases for an entire week to mandate that everyone ship code using agents.
Used-car platform Kavak took an even more drastic approach. In late 2022, it rolled out several AI assistants (copilots) to support employees, but staff barely used them. The CEO chose to bypass the copilot stage altogether and put AI agents directly on the front line of customer interactions, leaving no safety net to fall back on human agents if the system failed. The company paid a punishing price: revenue growth ground to an absolute halt across 2023. Today, AI agents handle 90 to 95 percent of customer interactions at Kavak, and its workforce has dropped from 10,000 to roughly 3,500.
Kavak’s path is an example of pushing from within what startups do from without: bypassing tools and turning the work entirely over to agents. The cost of doing so was immense. By contrast, transforming an organization by redefining human roles, as Konecta did, is inevitably slow.
The true advantage of an AI native is not that its founders or engineers are smarter than those at incumbent firms. It is the simple fact that nobody’s compensation or performance evaluation is tied to hours worked. The massive wall of internal resistance blocking legacy businesses does not exist for an AI native from day one.
5. The Cards Incumbents Still Hold
Are incumbents doomed to be pushed aside without recourse? I do not believe so. Even AI-native firms ultimately rely on human beings for the final sign-off and accountability. The resource that will become scarcest in the market is not the time required to do the work, but the people who take responsibility for the outcome—and incumbents already hold that resource in their hands.
The founder of Norm Ai, which created Norm Law, asserts that “nothing goes out the door without that human supervision by a barred attorney.” Harper similarly assigns paperwork and client follow-ups to AI agents, but licensed personnel make the final call. The experienced senior brokers and underwriters the company hires do not handle clients one by one; instead, they design evaluation criteria and routing rules for the AI. Crescendo also requires human sign-off before any customer response improvements developed by AI agents are deployed into production.
Crescendo’s acquisition of PartnerHero fits the same logic. In industries where regulatory licenses, established client networks, and accumulated operational data matter, buying an incumbent and rebuilding it from the inside can be faster than entering from scratch.
To be sure, most of today’s AI-native companies were founded between 2023 and 2025 and remain early-stage. Their operating track records are short, and many of their public claims remain self-reported.
Incumbents already possess what startups must spend capital to acquire: institutional licenses, loyal clients, and seasoned professionals who can sign off on outcomes and take responsibility. If incumbents continue selling these assets by the hour or by headcount, they will soon lose the work itself. But if they transition to a business model that prices outcomes and accountability, the cards they hold become their most formidable defense and weapon.
Conclusion — How Do You Make Money?
This industry restructuring is only beginning. We will see a flood of startups taking both paths at once: AI natives attacking markets from the outside, and startups acquiring incumbents to overhaul them from within.
During the mobile revolution, what incumbents lacked was not mobile coding talent. They simply lacked the resolve to dismantle and rebuild their business models at the expense of short-term profits. If that hesitation repeats itself today, the damage will not stop at losing customer touchpoints. The work itself will be absorbed by AI natives, leaving no role behind even as a supplier.
Leaders of incumbent industries need to ask themselves right now: are we selling the hours we put in, or the accountable outcomes we produce? If you cannot answer that question, your industry will be next.
References
- Bisnow, “After IPO, Airbnb Is Now Worth More Than Marriott, Hilton And Hyatt Combined” (2020-12-10)
https://www.bisnow.com/national/news/hotel/airbnb-valuation-skyrockets-huge-ipo-107052 - City A.M., “Delivery Hero takes a bite out of Asian market with $4bn Woowa deal” (2019-12-13)
https://www.cityam.com/delivery-hero-takes-a-bite-out-of-asian-market-with-4bn-woowa-deal/ - Clayton M. Christensen, The Innovator’s Dilemma (1997)
- Foundation Capital, “AI leads a service as software paradigm shift”
https://foundationcapital.com/ai-service-as-software/ - AX Field Notes, AI Natives: Norm Law, Harper, Crescendo
https://ax.yumes.net/natives/norm-law/
https://ax.yumes.net/natives/harper/
https://ax.yumes.net/natives/crescendo/ - AX Field Notes, Cases: Konecta, Warp, Affirm, Kavak
https://ax.yumes.net/cases/konecta-bcg/
https://ax.yumes.net/cases/warp-firstround/
https://ax.yumes.net/cases/affirm-retooling-week/
https://ax.yumes.net/cases/kavak-a16z/ - BCG X, “How One CX Provider Scaled AI Across 28 Countries”
https://www.bcg.com/x/mark-your-moment/scaling-ai-global-cx-operations - First Round, “Start With a Prompt: Inside How Warp’s CEO Follows His Own AI Coding Mandate” (2025-10-08)
https://www.firstround.com/ai/warp - Affirm Tech Blog, “How Affirm Retooled its Engineering Organization for Agentic Software Development in One Week” (2026-04-27)
https://medium.com/affirmengineering/how-affirm-retooled-its-engineering-organization-for-agentic-software-development-in-one-week-1fd35268fde6 - a16z Podcast, “From Copilots to Agents: Rebuilding the Company Around AI” (2026-02-18)
https://a16z.com/podcast/from-copilots-to-agents-rebuilding-the-company-around-ai/